
Cheyenne’s Super-Jumbo market is defined not by a dense concentration of $10M trophy estates — it’s defined by complexity. The buyers who need Super-Jumbo financing in Laramie County include business owners with multiple entities and non-W-2 income, senior executives and civil service officials whose compensation includes deferred components, retiring military officers with blended pension and investment portfolio profiles, and buyers pursuing estate-scale acreage builds where the land, infrastructure, and custom construction cost collectively push well above the standard Jumbo tier. Wyoming’s zero state income tax and asset-friendly legal environment — the state leads many rankings for dynasty trust structures — attract a specific tier of high-net-worth buyer for whom standard documentation programs don’t reflect their actual financial picture.
Super-Jumbo programs are the solution when the loan amount, the income structure, or both require underwriting outside the standard Jumbo framework. Ryan Lehrman, NMLS #235295, works directly with these buyers to identify the program structure — full doc, asset depletion, bank statement, or pledged asset — that matches the actual transaction.
Super-Jumbo financing generally refers to loans above $3M, though program thresholds vary by lender. In Cheyenne’s context, the relevance of Super-Jumbo programs extends to buyers whose income documentation complexity — not just loan size — puts them outside standard Jumbo underwriting. A business owner purchasing a $1.5M acreage build with business distribution income and significant retained earnings is a Super-Jumbo borrower by documentation type even if not by loan amount.
Asset depletion programs convert verified investment portfolio balances into qualifying monthly income. Bank statement programs use 12 or 24 months of business and personal deposits to establish income for self-employed borrowers. Pledged asset programs allow brokerage assets to serve as collateral without liquidation. These tools exist precisely for buyers whose net worth is real and whose ability to repay is unambiguous — but whose tax returns don’t reflect a simple, consistent income stream.
Fixed and ARM structures for large-acreage custom builds in Laramie County — Ironhorse, Crown S Ranch, Lonesome Dove Ranches, and legacy agricultural parcels throughout southeastern Wyoming. Loan amounts from $3M and above.
For buyers with substantial investment portfolios, retirement accounts, or real estate equity who prefer not to liquidate positions to meet income documentation requirements. Verified assets are divided across a qualifying period to establish monthly income.
For buyers with deferred compensation, business distributions, carried interest, or multiple income sources. Documentation structured around the actual income profile rather than a two-year average that may underrepresent current earning capacity.
Super-Jumbo One-Time Close Construction financing for estate-scale builds on large Laramie County parcels. Single close, rate lock before construction begins, automatic conversion at certificate of occupancy.
Cheyenne’s upper-tier buyers are concentrated in a few distinct profiles: retiring military officers and senior civil service officials who’ve spent careers accumulating equity across multiple PCS markets and are now landing in a zero-tax state; business owners from Colorado and elsewhere establishing Wyoming residency and purchasing a primary property to support that residency claim; and Cheyenne-rooted professionals — attorneys, physicians, engineers, contractors — whose income has grown over decades into a range that standard Jumbo documentation handles poorly.
The properties that serve this buyer include the Ironhorse luxury rural subdivision west of town, legacy ranch-adjacent parcels in the Laramie County foothills, and estate-scale custom builds throughout the southeastern Wyoming corridor. For buyers relocating from Colorado, a Wyoming primary residence also eliminates ongoing state income tax exposure — a permanent financial benefit that compounds year over year.
Asset depletion, bank statement, and pledged asset programs for complex-income Cheyenne buyers
Construction-to-permanent Super-Jumbo for large-acreage estate builds in Laramie County
Wyoming tax residency context incorporated into every consultation
Discreet, direct process — no handoffs, no committees
Experience structuring transactions for buyers whose financial profile requires creative documentation, not a checklist
NMLS #235295
Loan Amounts: $3M+ standard; complex-income programs available at lower amounts for non-W-2 borrowers
Credit: Typically 720+ for primary programs; stronger profiles produce better pricing
Income Documentation: Full doc, asset depletion, bank statement (12 or 24 months), or pledged asset — program matched to borrower profile
Reserves: 12–24 months PITI in verified liquid or near-liquid assets typically required post-close at this tier
Profile Review — Assess income documentation type, asset structure, target property, and entity considerations. Wyoming LLCs and trusts taking title require specific documentation.
Program Selection — Identify the qualification pathway and structure down payment and reserve strategy accordingly.
Pre-Approval — Complete underwriting review before property search or offer. Sellers of upper-tier Cheyenne and Laramie County properties expect committed pre-approval.
Rate Lock — Coordinate timing with transaction and construction timeline. Acreage builds may favor ARM structures during construction with a conversion strategy at certificate of occupancy.
Closing — Wyoming deed of trust structure. Coordinate with title and legal counsel if an entity is taking title.
Yes. Asset depletion programs are available for Cheyenne buyers with substantial, verifiable investment portfolios, retirement accounts, or real estate equity. Assets are divided by a qualifying period to produce a monthly income figure. This is particularly applicable for buyers who are retired, self-employed, or transitioning between income sources.
Wyoming residency intent must be documented when financing a primary residence — this affects program eligibility, rate, and down payment. For buyers relocating from Colorado or other high-tax states specifically to establish Wyoming residency, we structure these transactions from the beginning with residency intent properly reflected in the file.
Yes. Bank statement programs using 12 or 24 months of personal and/or business deposits are available for self-employed buyers. These programs typically carry slightly higher rates than full-doc Jumbo but remain competitive and are far preferable to adjusting W-2 income artificially through business restructuring.
Super-Jumbo transactions benefit from early engagement. Let’s have a confidential conversation about your property and financial profile.
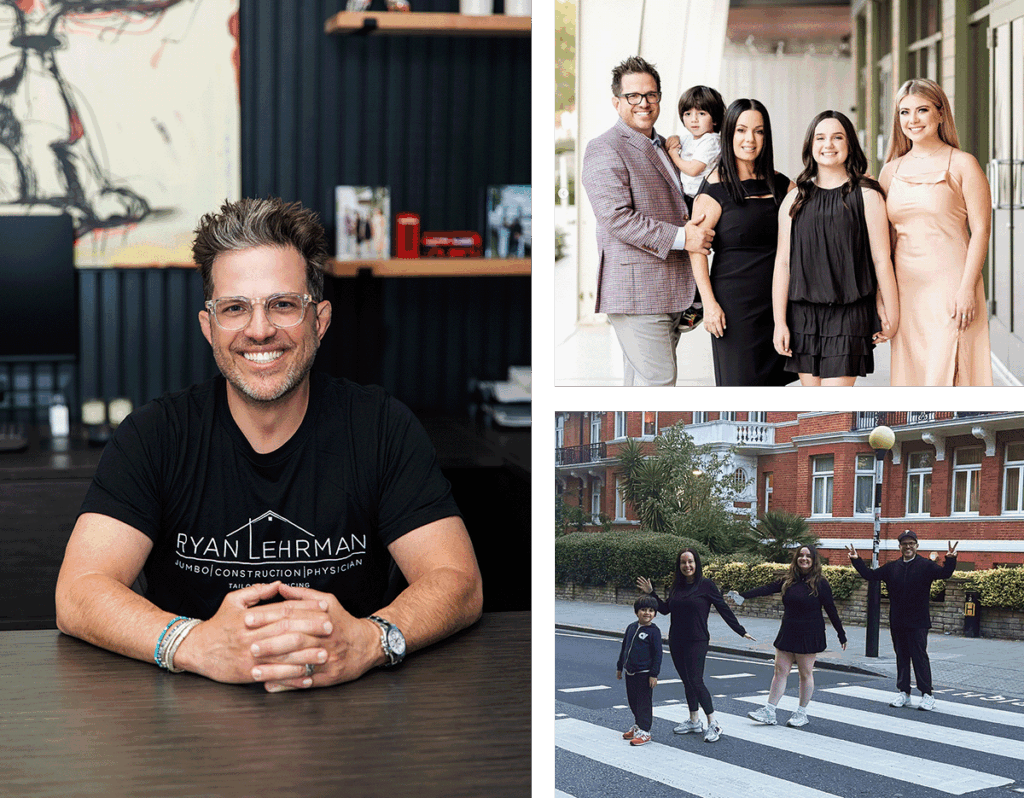
Originally from Harrisburg, Pennsylvania, I moved to Phoenix to attend Arizona State University and have proudly called Phoenix home ever since.
My journey into the mortgage industry began with a friend’s encouragement, who saw how my energy and people-first mindset could make a difference. He was right — I found my calling.
I’ve always embraced what makes me different. With ADHD as my secret weapon, I thrive in fast-paced, detail-heavy environments. I’ve built my career on clear communication, creative problem-solving, and putting clients first, always.
Outside of work, my greatest motivation is my wife and three amazing kids. I’d be honored to help guide you through your lending journey with care, clarity, and commitment.
Who we are
Our website address is: https://staging.loansbylehrman.com/
Embedded content from other websites
Articles on this site may include embedded content (e.g. videos, images, articles, etc.). Embedded content from other websites behaves in the exact same way as if the visitor has visited the other website.
These websites may collect data about you, use cookies, embed additional third-party tracking, and monitor your interaction with that embedded content, including tracking your interaction with the embedded content if you have an account and are logged in to that website.
SMS Privacy
I respect your privacy. I will not share or use your mobile number for any other purpose. I will only use information you provide to transmit text messages. Nonetheless, I reserve the right at all times to disclose any information as necessary to satisfy any law, regulation or governmental request, to avoid liability, or to protect my rights or property. When you complete forms online or otherwise provide me information in connection with the Service, you agree to provide accurate, complete and true information. You agree not to use a false or misleading name or a name that you are not authorized to use. If I, in my sole discretion, believe that any such information is untrue, inaccurate or incomplete, I may refuse you access to the Service and pursue any appropriate legal remedies.
Analytics tracking
Our website uses analytics tools such as Google Analytics to better understand how visitors interact with our site. These tools collect data through cookies and similar technologies, including information about on-site activity and, in some cases, IP addresses. We use this data to improve user experience, monitor performance, and track conversions. Visitors who prefer not to be tracked can opt out by using the Google Analytics opt-out browser add-on or other available opt-out methods.