
Sun Valley is the most expensive real estate market in Idaho — and it is not close. Through late 2025, Ketchum’s 83340 ZIP code carried the state’s highest median list price at $2.28 million. The city of Sun Valley itself posted a $1.5 million median. Blaine County’s full-year 2024 median sale price crossed $1 million for the first time in its history — the county’s total taxable assessed value reached $25.8 billion, up 13.47% in a single year. The broader Sun Valley area recorded a median sold price of approximately $1.6 million as of December 2025, up 10.8% year-over-year.
The financing reality these numbers create is significant and widely misunderstood. Blaine County is not a high-cost county for conforming loan purposes — the FHFA applies the standard $832,750 baseline limit here, not the elevated $1,249,125 limit that Teton County carries. Idaho has exactly one high-cost county. Blaine County is not it. In a market where the median list price is $2.28 million and the entry-level Elkhorn condo starts in the mid-$300,000s only in the most basic unit configurations, the conforming limit of $832,750 is breached on virtually every meaningful single-family home purchase in Ketchum and Sun Valley. Every acquisition above that threshold requires a Jumbo or Super-Jumbo loan — and in Sun Valley, that is almost every acquisition.
Sun Valley Resort was founded December 21, 1936, by W. Averell Harriman of the Union Pacific Railroad — who sent Austrian count Felix Schaffgotsch to find the ideal American ski mountain and received the reply: “This is the place.” The resort introduced America’s first chairlift, opened on the same day as the Sun Valley Lodge, and has operated continuously for 89 seasons. It remains privately owned by the R. Earl Holding family (Grand America Hotels and Resorts) and sits on Bald Mountain — 9,150 feet at the summit, a 3,400-foot vertical drop, 2,829 skiable acres, 121 trails, and 17 lifts. Sun Valley has been a seasonal residence for Ernest Hemingway, Tom Hanks, Clint Eastwood, Bruce Willis, Warren Buffett, and Bill Gates. It is compared by luxury real estate professionals to Aspen, Vail, and Jackson Hole — and typically offers more square footage, larger lots, and more direct mountain access at a lower price point than any of them.
The buyer pool here is unlike any other market in the Idaho build: cash-heavy, second-home dominant, and drawn from Silicon Valley, Wall Street, and the Pacific Coast rather than from the Treasure Valley employment base. A meaningful share of Sun Valley transactions close in cash — the 732 active short-term rental properties averaging $638 per night and 50% occupancy produce monthly gross revenue around $40,685, per AirDNA data. Buyers who do finance need Super-Jumbo programs, asset-depletion qualifying, and lender relationships that understand resort market appraisal dynamics in a market where comparable sales are limited and prices are set by scarcity.
I’m Ryan Lehrman, NMLS #235295. Sun Valley requires a fundamentally different approach from every other Idaho market in this build — and getting the program right before the offer is submitted is what makes the difference.
Super-Jumbo portfolio lender relationships for Ketchum and Sun Valley's $1M–$8M+ price tier
Asset-depletion qualifying for cash-heavy buyers who prefer leveraged financing on second-home acquisitions
Blaine County's $832,750 conforming limit framed correctly — every significant Sun Valley/Ketchum purchase requires Jumbo or Super-Jumbo financing
Second-home and vacation property Jumbo and Super-Jumbo programs available
St. Luke's Wood River Medical Center physician loans for lifestyle-driven physician recruits choosing the Wood River Valley
Interest-only Super-Jumbo structures for buyers who want capital flexibility during initial ownership
Resort appraisal expertise — limited comparable sales in the Blaine County upper-tier market require lender experience with this dynamic
Discretion and confidentiality appropriate for Sun Valley's high-profile buyer profile
Licensed in Idaho and multiple states
Ryan Lehrman, NMLS #235295
With the standard conforming limit at $832,750 and the Sun Valley area’s median sold price around $1.6 million, every typical Sun Valley and Ketchum home purchase requires Jumbo financing. Entry-level condos in Elkhorn can be found near the conforming threshold in some configurations, but single-family residences, ski-close townhomes, and Warm Springs base area properties start their meaningful price range well above it. For buyers financing between $832,751 and $2 million, standard Jumbo programs apply with asset-depletion qualifying, second-home occupancy structures, and resort appraisal methodology.
Elkhorn estate lots have sold above $8 million. Ketchum’s median list price of $2.28 million means the typical single-family purchase in that market — not the upper tier, the median — is a Super-Jumbo transaction. White Clouds new construction commands $3 million and above. Warm Springs ski-close estates and Bald Mountain view properties are priced at levels that require Super-Jumbo programs with portfolio lender relationships, interest-only options, and asset-depletion qualifying structures designed for high-net-worth buyers who may be financing alongside significant liquid assets and investment portfolios.
St. Luke’s Wood River Medical Center in Ketchum — a critical access hospital at 100 Hospital Drive serving the Wood River Valley — operates with 79 physicians across 28 specialties and a 92% patient recommendation rate, providing a level of specialty care rarely available in a community of this size. The physicians who practice here are a specific profile: established providers who have chosen the Wood River Valley for its lifestyle, its four-season recreation, and its proximity to 730,000 acres of the Sawtooth National Recreation Area — not because it is the fastest career progression. Physician loans serve these buyers with no PMI, deferred student loan exclusion, and contract qualifying at the price levels the Sun Valley market demands.
New construction in Sun Valley is constrained by geography, zoning, conservation easements, and the limited footprint of the Wood River Valley. What does exist — White Clouds new contemporary mountain residences designed by Buffalo Rixon of RLB and built by MTN Origins, custom builds on remaining estate lots in Elkhorn, and rebuild projects on Wood River Valley parcels where demolition of existing structures makes room for new construction — represents the finite supply of new residential real estate in one of America’s most capacity-constrained resort markets. One-Time Close Construction financing serves buyers who can secure a build site and want to lock the permanent rate before construction begins.
The single most important financing fact about Sun Valley is also the most commonly misunderstood: Blaine County’s 2026 conforming loan limit is $832,750 — the same standard baseline that applies in Canyon County, Twin Falls County, and every other non-high-cost Idaho county. Sun Valley did not receive a high-balance exception. Teton County, which borders Wyoming and serves the Jackson Hole area, is Idaho’s only high-cost county at $1,249,125. Blaine County, home to the most expensive residential real estate in the state, is at the baseline.
In practice, this means that a buyer financing a $1.5 million Sun Valley home — which is the area median — with 20% down needs a loan of $1.2 million. That is a Super-Jumbo transaction at Blaine County’s conforming limit, not a standard Jumbo. A buyer financing the Ketchum median of $2.28 million with 20% down needs a loan of $1.824 million. Also Super-Jumbo territory. The entry point for a meaningful single-family purchase in Sun Valley or Ketchum with any financing at all is above the standard Jumbo threshold for most buyers.
A meaningful share of Sun Valley transactions close in cash. The buyer profile — Silicon Valley liquidity events, Wall Street compensation, coastal home sale proceeds, family wealth — often brings the ability to pay cash and the strategic question of whether to do so. The argument for financing even in a cash position is clear: leveraged capital preserved for higher-returning investments while a fixed-rate mortgage finances a depreciating-liability appreciation play. This is the conversation high-net-worth buyers have with their advisors, and it is one that a Super-Jumbo lender should be able to participate in meaningfully — not just execute a transaction.
Many Sun Valley properties are purchased as second homes, seasonal retreats, or investment properties with short-term rental income. Financing structures for these uses differ from primary residence Jumbo and Super-Jumbo: higher down payments, different reserve requirements, and specific occupancy documentation. The 732 active STR properties in the Wood River Valley — averaging $638 per night and 50% occupancy according to AirDNA — produce monthly gross revenues around $40,685, making the rental income angle a meaningful part of the acquisition conversation for buyers who want the Sun Valley lifestyle alongside an income-producing asset.
Blaine County's 2026 conforming loan limit is $832,750 — the standard Idaho baseline. Sun Valley is not a high-cost county. This means any loan above $832,750 is a Jumbo loan, and the Ketchum area's $2.28 million median list price means virtually every single-family home purchase in Sun Valley or Ketchum requires Jumbo or Super-Jumbo financing. Only the most basic entry-level Elkhorn condo configurations approach the conforming threshold.
All three markets have comparable luxury price tiers, but their conforming loan limit structures differ significantly. Jackson Hole sits in Teton County, Wyoming, which is a high-cost county with a $1,249,125 conforming limit. Aspen is in Pitkin County, Colorado, which also carries a high-cost designation. Blaine County, Idaho does not — the $832,750 standard limit applies. This means Sun Valley buyers reach Super-Jumbo territory on a lower loan amount than equivalent Aspen or Jackson Hole buyers, making the Super-Jumbo lender relationship comparatively more important in the Sun Valley market.
Yes. Second-home and vacation-property Jumbo and Super-Jumbo programs are available for buyers purchasing in Sun Valley as a seasonal or recreational residence. These programs typically require higher down payments (20–30%), more robust reserve documentation, and specific occupancy representations. Short-term rental income from the property can sometimes be factored into qualifying income with proper documentation of rental history or projected revenue for new purchases.
Yes. Asset-depletion programs convert verified liquid assets — brokerage accounts, money market funds, retirement accounts — into a qualifying monthly income figure without requiring traditional W-2 or self-employment income. This structure is frequently used by Sun Valley's buyer profile: liquidity-event recipients, retired executives, and investors who have significant asset positions but prefer not to qualify on employment income alone for a second-home acquisition.
I’m here to support you every step of the way. If you’re ready to turn your home financing goals into your new reality, let’s work together.
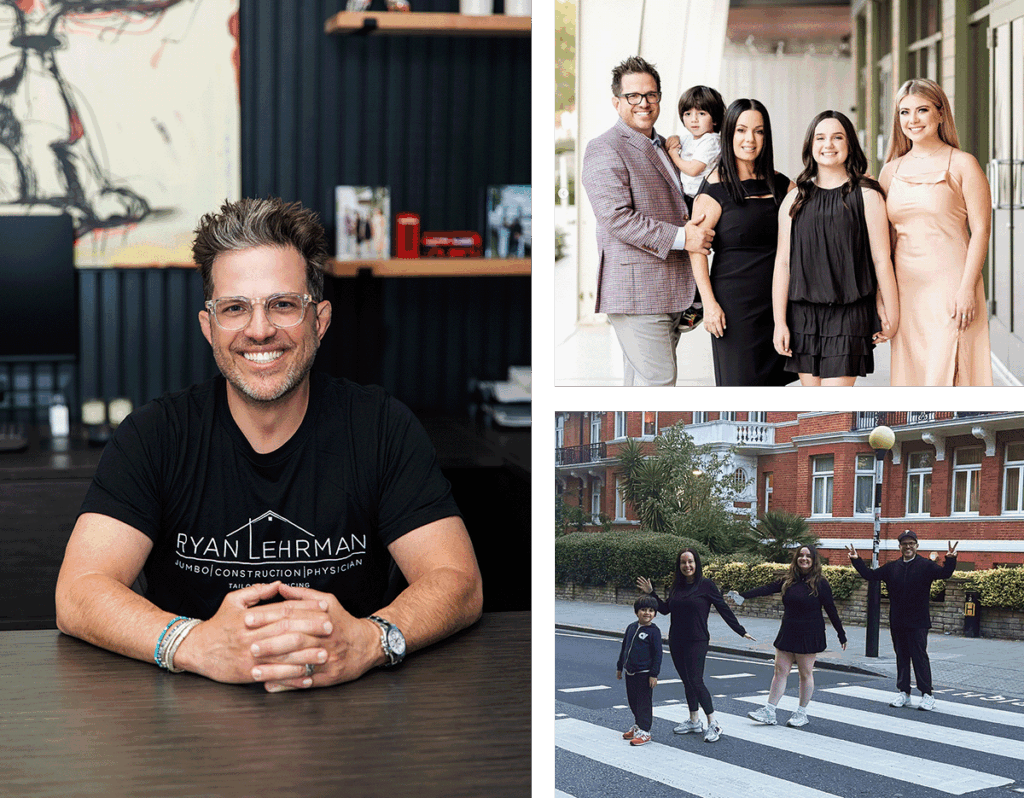
Originally from Harrisburg, Pennsylvania, I moved to Phoenix to attend Arizona State University and have proudly called Phoenix home ever since.
My journey into the mortgage industry began with a friend’s encouragement, who saw how my energy and people-first mindset could make a difference. He was right — I found my calling.
I’ve always embraced what makes me different. With ADHD as my secret weapon, I thrive in fast-paced, detail-heavy environments. I’ve built my career on clear communication, creative problem-solving, and putting clients first, always.
Outside of work, my greatest motivation is my wife and three amazing kids. I’d be honored to help guide you through your lending journey with care, clarity, and commitment.
Who we are
Our website address is: https://staging.loansbylehrman.com/
Embedded content from other websites
Articles on this site may include embedded content (e.g. videos, images, articles, etc.). Embedded content from other websites behaves in the exact same way as if the visitor has visited the other website.
These websites may collect data about you, use cookies, embed additional third-party tracking, and monitor your interaction with that embedded content, including tracking your interaction with the embedded content if you have an account and are logged in to that website.
SMS Privacy
I respect your privacy. I will not share or use your mobile number for any other purpose. I will only use information you provide to transmit text messages. Nonetheless, I reserve the right at all times to disclose any information as necessary to satisfy any law, regulation or governmental request, to avoid liability, or to protect my rights or property. When you complete forms online or otherwise provide me information in connection with the Service, you agree to provide accurate, complete and true information. You agree not to use a false or misleading name or a name that you are not authorized to use. If I, in my sole discretion, believe that any such information is untrue, inaccurate or incomplete, I may refuse you access to the Service and pursue any appropriate legal remedies.
Analytics tracking
Our website uses analytics tools such as Google Analytics to better understand how visitors interact with our site. These tools collect data through cookies and similar technologies, including information about on-site activity and, in some cases, IP addresses. We use this data to improve user experience, monitor performance, and track conversions. Visitors who prefer not to be tracked can opt out by using the Google Analytics opt-out browser add-on or other available opt-out methods.