
Santa Clara County’s 2026 conforming loan limit sits at the statutory ceiling of $1,249,125, the maximum allowed anywhere in the country. In most high-cost counties that ceiling still leaves room below the local median price. Not in Palo Alto. With the citywide median sale price near $3.15 million to $3.5 million, and established neighborhoods like Old Palo Alto and Crescent Park posting median sale prices of $5.6 million and $5.9 million, a Jumbo loan is simply what financing a home in this city looks like.
I underwrite Jumbo loans for Palo Alto buyers with an understanding of how this specific market pays its residents: RSU vesting and stock options from Stanford Research Park employers like Tesla, HP, and VMware; founder and executive equity from Palo Alto’s startup ecosystem; and, for a smaller number of buyers, physician compensation tied to Stanford Health Care. I also understand how Palo Alto’s compact, largely built-out lots and teardown-rebuild culture affect appraisal.
A Jumbo mortgage is any loan amount above Santa Clara County’s conforming limit of $1,249,125, placing it outside Fannie Mae and Freddie Mac purchasing guidelines. Because Santa Clara County already sits at the FHFA’s high-cost ceiling, there’s no higher conventional tier — Jumbo financing in Palo Alto begins at the same threshold as the most expensive counties in the nation.
Key Features:
Loan amounts above $1,249,125 for a single-family home in Santa Clara County
Down payments typically starting around 10-20%, depending on loan amount and property type
Credit score requirements generally starting at 700, often higher for larger loan amounts
Underwriting that can incorporate RSU vesting, stock options, and founder equity documentation
Financing available for existing single-family homes, condos, and teardown-rebuild construction
For Palo Alto purchases in the $1.25 million to $3 million range, which covers a meaningful share of the city’s more modest single-family inventory in neighborhoods like Midtown and Barron Park.
For financing above $3 million, common throughout Old Palo Alto and Crescent Park, where estate-level teardown lots and finished luxury homes require more flexible underwriting. Full detail is available on our Super-Jumbo Mortgage Loans page.
For physicians and researchers affiliated with Stanford Health Care or Stanford Medicine Children’s Health who need Jumbo-level financing with the reduced down payment structure of a physician loan.
Old Palo Alto
One of the city's most established neighborhoods, with a median sale price around $5.6 million and single-family homes averaging well above that; this is also one of the city's most active teardown-rebuild corridors given its proximity to downtown and Stanford.
Crescent Park
Palo Alto's highest-priced neighborhood, with median sale prices reported near $5.9 million to $5.93 million, known for larger lots, historic charm, and mature tree-lined streets; buyers here should note that roughly a third of properties carry some flood risk, which factors into insurance and underwriting.
Professorville
A designated historic district near Stanford, prized for early-20th-century architecture, where preservation rules add another layer of consideration to any renovation or rebuild financing.
Barron Park
A semi-rural pocket of winding roads and mature trees that offers relatively more accessible entry points into Palo Alto's Jumbo tier compared to Old Palo Alto or Crescent Parkoriented professionals. At the $1 million-plus price points common in Table Mesa, jumbo financing is routinely required even for mid-range purchases in the neighborhood.
Jumbo underwriting built around Santa Clara County's high-cost conforming ceiling
Experience documenting RSU, stock option, and founder equity income for Palo Alto's tech and startup borrowers
Familiarity with Palo Alto's teardown-rebuild culture and how it affects appraisal and construction-adjacent financing
Direct communication throughout your file
Competitive Jumbo pricing sourced across multiple investor programs
Confidential pre-approval conversations before you make an offer
Ryan Lehrman, NMLS #235295
Credit profile: Generally a 700+ credit score, with stronger pricing available above 740
Down payment: Typically 10-20%, varying by loan amount and property type
Income documentation: Two years of tax returns, current pay stubs, and — for RSU, stock option, or founder equity income — vesting schedules and award or cap table documentation
Reserves: Lenders commonly require 6-12 months of mortgage payments in liquid reserves for Palo Alto's larger Jumbo loans
Initial consultation — We review your income structure, target neighborhoods, and loan amount to identify the right Jumbo program.
Documentation and pre-approval — We assemble your income, asset, and credit documentation, including RSU, stock option, or equity history if applicable.
Property identification — You shop with a strong pre-approval letter in a market where Old Palo Alto and Crescent Park homes routinely sell in 9-14 days.
Underwriting and appraisal — We coordinate underwriting with attention to Palo Alto-specific factors, including teardown-rebuild lots and flood zone considerations in Crescent Park.
Closing — We finalize your Jumbo financing and get you to the closing table on your timeline.
It depends on the loan amount, but given that Palo Alto's median price runs well above $3 million, many qualifying buyers show substantial household income, often supplemented heavily by RSU vesting, stock options, or founder equity rather than base salary alone. I can review your specific numbers and tell you what loan amount your income supports.
Yes, with the right documentation. Lenders generally want a two-year history of vesting or grants, along with evidence they're likely to continue. I structure this regularly for Palo Alto borrowers at companies based in the Stanford Research Park and for founders with equity in earlier-stage companies.
It can. Financing a teardown purchase itself is generally a standard Jumbo purchase loan, but the rebuild typically requires separate construction financing, which I can structure as a One-Time Close loan so you're not managing two separate closings.
Ready to finance your upper-tier Palo Alto property? Schedule a confidential consultation today.
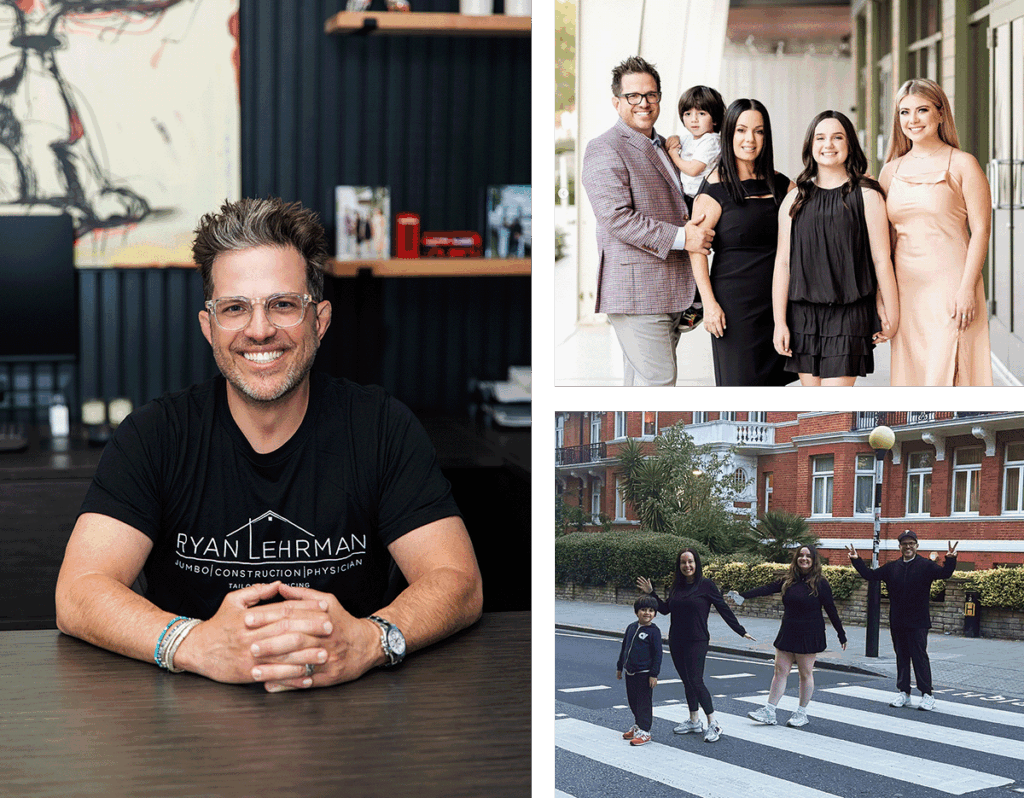
Originally from Harrisburg, Pennsylvania, I moved to Phoenix to attend Arizona State University and have proudly called Phoenix home ever since.
My journey into the mortgage industry began with a friend’s encouragement, who saw how my energy and people-first mindset could make a difference. He was right — I found my calling.
I’ve always embraced what makes me different. With ADHD as my secret weapon, I thrive in fast-paced, detail-heavy environments. I’ve built my career on clear communication, creative problem-solving, and putting clients first, always.
Outside of work, my greatest motivation is my wife and three amazing kids. I’d be honored to help guide you through your lending journey with care, clarity, and commitment.
Who we are
Our website address is: https://staging.loansbylehrman.com/
Embedded content from other websites
Articles on this site may include embedded content (e.g. videos, images, articles, etc.). Embedded content from other websites behaves in the exact same way as if the visitor has visited the other website.
These websites may collect data about you, use cookies, embed additional third-party tracking, and monitor your interaction with that embedded content, including tracking your interaction with the embedded content if you have an account and are logged in to that website.
SMS Privacy
I respect your privacy. I will not share or use your mobile number for any other purpose. I will only use information you provide to transmit text messages. Nonetheless, I reserve the right at all times to disclose any information as necessary to satisfy any law, regulation or governmental request, to avoid liability, or to protect my rights or property. When you complete forms online or otherwise provide me information in connection with the Service, you agree to provide accurate, complete and true information. You agree not to use a false or misleading name or a name that you are not authorized to use. If I, in my sole discretion, believe that any such information is untrue, inaccurate or incomplete, I may refuse you access to the Service and pursue any appropriate legal remedies.
Analytics tracking
Our website uses analytics tools such as Google Analytics to better understand how visitors interact with our site. These tools collect data through cookies and similar technologies, including information about on-site activity and, in some cases, IP addresses. We use this data to improve user experience, monitor performance, and track conversions. Visitors who prefer not to be tracked can opt out by using the Google Analytics opt-out browser add-on or other available opt-out methods.